Your car insurance covers a rented Tesla in Los Angeles only if your policy extends the relevant coverage to that vehicle, rental arrangement, driver, and trip. Liability coverage and protection for damage to the Tesla are separate questions; your deductible, exclusions, and obligations under the rental agreement still matter.
- Does car insurance cover a rented Tesla? Your policy’s rental provisions decide, not the Tesla badge.
- Check liability and rental vehicle damage separately before your Los Angeles pickup.
- Credit card rental benefits are not a substitute for checking liability coverage.
- The Suite Escape suits travelers seeking concierge Tesla rentals; confirm insurance separately from delivery and mileage benefits.
The Suite Escape is best for Los Angeles travelers seeking luxury Tesla rentals with concierge delivery and unlimited miles. Those service benefits simplify your trip, but they do not establish what your own insurance covers.
Does your car insurance cover a rented Tesla in LA?
Your policy must cover the actual rental—not simply the act of driving someone else’s car. For a 2026 booking, ask your insurer to assess the rental company, Tesla model, rental dates, intended use, and every proposed driver.
A policy’s declarations page summarizes purchased coverage. Its policy wording and endorsements explain how that coverage applies to a rental. Read those alongside the rental agreement rather than treating an insurance card as the complete answer.
| Coverage or protection | Best for checking | What it addresses | Limit to confirm |
|---|---|---|---|
| Personal auto liability coverage | Injury and property-damage responsibility | Claims involving harm you cause to others, when the policy applies | Whether coverage extends to this rental and its drivers |
| Personal collision and comprehensive coverage | Damage to the rented Tesla | Covered collision losses and covered non-collision events | Rental eligibility, deductible, exclusions, and valuation terms |
| Credit card rental benefit | Potential rental vehicle damage benefits | Eligible losses described in the card’s benefit guide | Vehicle exclusions, payment requirements, rental duration, and claim conditions |
| Rental company damage waiver | Contractual responsibility for vehicle damage | Responsibility the rental company agrees to waive under its terms | Excluded conduct, remaining obligations, and whether liability is separate |
These protections serve different purposes. A damage waiver is not the same thing as liability insurance, and a credit card benefit does not automatically replace either one.
For a closer look at those distinctions, compare Tesla rental insurance and protection plans against the documents for your specific booking.
Why this matters before your LA pickup
A smooth arrival starts with a clear answer about who handles a claim. Concierge delivery, an accepted reservation, and permission to drive do not establish the scope of your personal insurance.
For your 2026 trip, settle the insurance question before choosing any optional protection. You need to know both what your policy covers and which responsibilities remain yours under the rental agreement.
Think beyond a collision. Theft, glass damage, parking damage, and charges associated with a vehicle being unavailable raise different policy and contract questions. Ask about each relevant category instead of relying on a general assurance that rentals are covered.
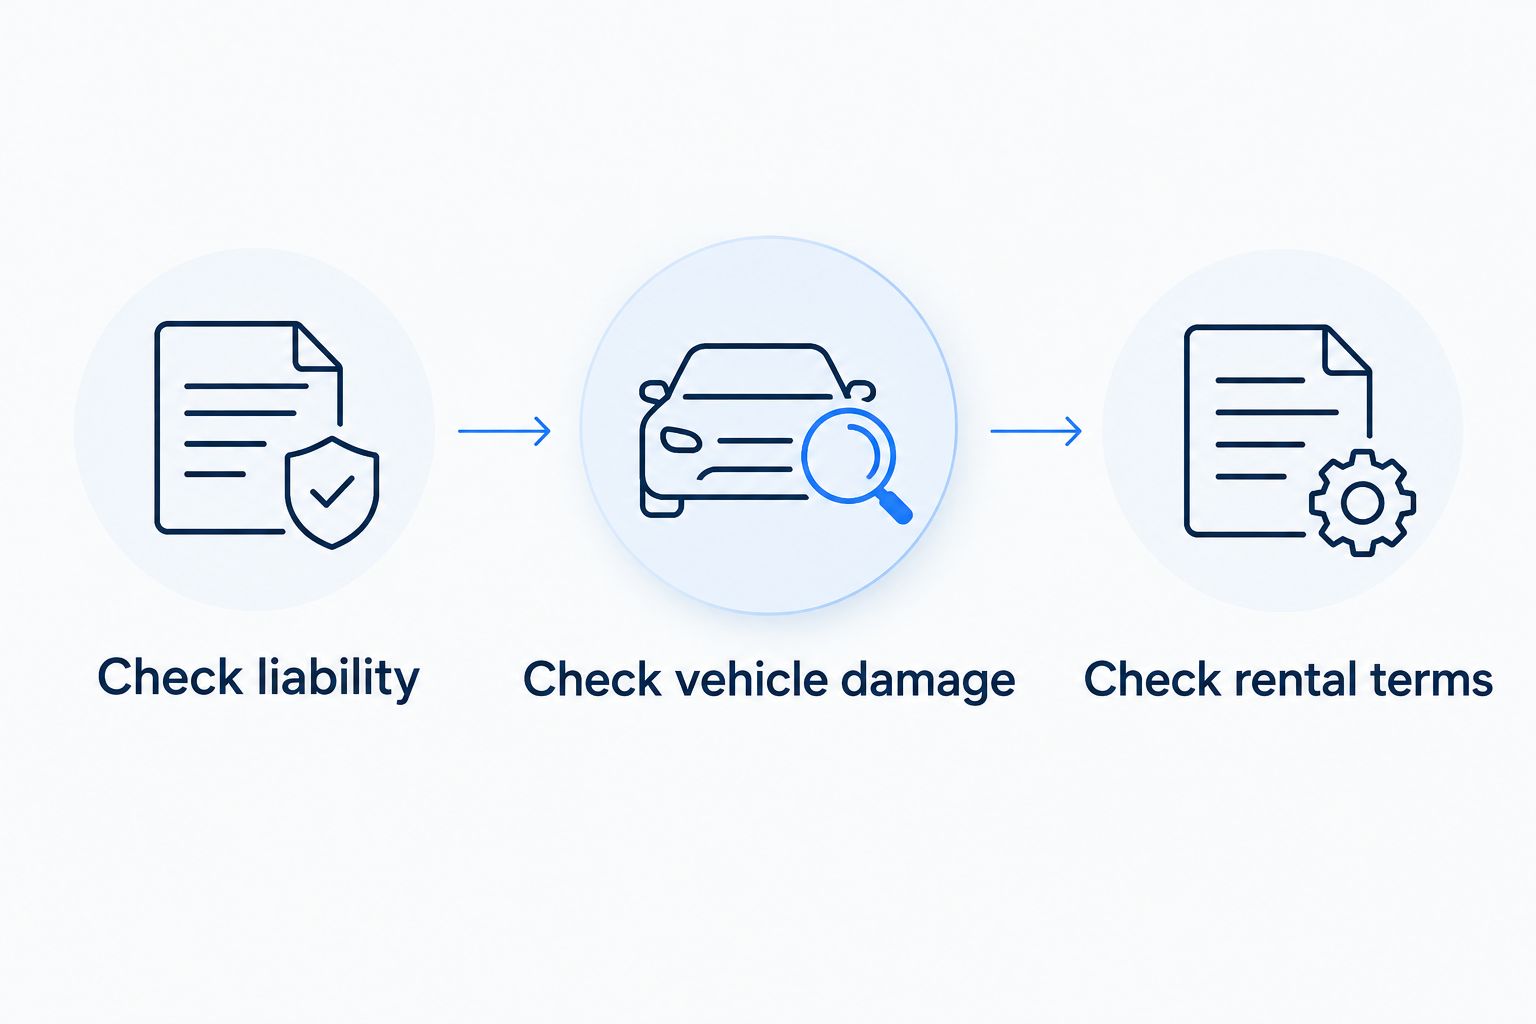
Start with 3 checks before you book
Use these 3 checks to turn a broad insurance question into a booking-specific answer. Keep the responses with your reservation so you can refer to the same information at delivery.
Check liability
Ask whether your bodily injury and property damage liability coverage applies while you drive the rented Tesla. Give the insurer the rental company’s name and explain whether the trip is personal, business-related, or a combination.
Do not confuse property damage liability with protection for the Tesla itself. They address different responsibilities. Ask the insurer to identify the applicable limits and any conditions affecting other authorized drivers.
Check vehicle damage
Ask whether your collision and comprehensive coverage extends to the exact rented vehicle. Name the model rather than saying only that you are renting an electric car.
Confirm the deductible and how the policy determines payment for a covered loss. Also ask about exclusions related to vehicle type, value, rental arrangement, or use; the relevant wording matters more than a broad description such as full coverage.
Check rental terms
Read the agreement for driver authorization, permitted use, incident reporting, and responsibility for damage. Then compare those obligations with the protection your insurer has confirmed.
Ask specifically about loss-of-use claims, administrative charges, towing, and diminished value. Do not assume every charge connected with an accident receives the same treatment as the physical repair.
Why rental Tesla insurance coverage varies
The useful question is not whether an insurer generally covers rentals. It is whether the policy covers your particular booking. These factors define what to ask:
- Purchased coverage: Liability, collision, and comprehensive coverage perform different jobs. Ask which purchased protections extend to the rental.
- Vehicle eligibility: Give the insurer the exact model and ask about vehicle-class or value restrictions.
- Rental arrangement: Identify the rental provider and contract structure rather than assuming all rental arrangements receive identical treatment.
- Driver authorization: Confirm both the rental company’s permission and the insurer’s treatment of every driver.
- Trip purpose: Describe personal travel, business use, or any planned activity accurately so the insurer can assess the correct terms.
- Duration and destination: Provide the full rental period and route, including travel outside California, and ask about applicable restrictions.
For a 2026 road trip, repeat this check if the booking changes. An added driver, extended rental, or different vehicle changes the facts behind the original coverage answer.
Can I use my credit card instead of personal car insurance?
A credit card rental benefit is not a complete substitute for checking your insurance. Read the benefit guide for the exact card you will use, not a general description of benefits associated with its payment network.
Ask whether the rented Tesla qualifies and how payment, reservation, and damage-waiver decisions affect eligibility. Confirm rental-duration restrictions and whether the benefit pays before or after other applicable insurance.
The advantage is a potential additional source of protection for eligible rental damage. The limitation is that eligibility and claim requirements are specific to the benefit. Separately confirm liability coverage rather than assuming a rental damage benefit covers injuries or damage to someone else’s property.
Before declining protection, have the card benefit administrator address the actual reservation. Keep the current benefit guide and the response you receive with your booking records.
Does a rental damage waiver replace my insurance?
A rental damage waiver addresses the responsibilities described in its contract; it does not automatically replace your insurance. Read what the rental company agrees to waive and what remains your responsibility.
A waiver’s practical benefit is clarity about specified vehicle-damage obligations when its conditions are met. Its limitation is scope: excluded uses, unauthorized drivers, reporting requirements, and other contract terms still need attention.
For a 2026 reservation, compare the waiver with your existing protection before accepting or declining it. Ask the rental provider to explain the difference between vehicle-damage protection and any liability protection offered. Make the decision from written terms, not the name of the package.
Keep 2 documents together: your coverage confirmation and rental agreement
Your coverage confirmation and rental agreement answer different questions. The insurer explains the policy; the rental company explains your contractual obligations. Keep both available on your phone before delivery.
Save the insurer’s response, relevant policy wording, reservation details, and any card benefit guide you intend to rely on. Written confirmation helps you preserve the facts discussed, but it does not replace or amend the policy itself.
At handover, photograph the exterior, wheels, glass, and cabin, then make sure existing damage is recorded through the provider’s process. Consistent documenting rental vehicle damage separates the vehicle’s handover condition from damage reported later; retain pickup and return records together.
Use clear, original images rather than relying on a quick walk-around from memory. Follow the rental company’s reporting procedure for anything you notice, and retain any acknowledgment alongside the agreement.
Does FSD (Supervised) change the insurance answer?
FSD (Supervised) does not establish insurance coverage or remove the driver’s responsibility to remain attentive. Confirm protection for the rented vehicle and permitted use just as you would before driving without assistance features.
The Suite Escape’s Tesla rentals include FSD (Supervised). Treat that as a driving-assistance feature, not an insurance provision or permission to disengage from driving. Ask your insurer and rental provider about any relevant use conditions before your 2026 pickup.
The convenience belongs in your driving plan; the coverage decision belongs in your policy review. Keep those decisions separate so a feature description never becomes an assumption about claim payment.
What should I ask my insurer before LAX delivery?
Give your insurer a precise description of the booking, then ask for a response tied to your policy. This keeps the conversation focused on an actual rental rather than a hypothetical borrowed vehicle.
Use this checklist:
- Identify the rental company, Tesla model, rental dates, and pickup location.
- Describe your intended route and whether the trip is personal or business-related.
- Name every person who expects to drive.
- Ask separately about liability and damage to the rented Tesla.
- Confirm deductibles, exclusions, and treatment of rental-related charges.
- Ask which policy provisions support the answer and save the response.
Repeat the same facts to any credit card benefit administrator whose protection you plan to use. Conflicting answers deserve clarification before pickup, not an assumption that the broader answer wins.
For your 2026 arrival, arrange the coverage review before delivery day. That leaves handover time for the vehicle condition record, controls, charging plan, and rental instructions.
What if I do not have a personal auto policy?
Without a personal auto policy, you need to establish applicable protection through other sources before driving. Ask the rental company what protection applies to the reservation and what additional protection is offered or required.
Do not assume a credit card rental benefit supplies liability insurance. International visitors should also ask their existing insurer whether any home-country policy extends to the US rental, then confirm the rental provider’s requirements separately.
If you cannot identify who covers liability and vehicle damage, pause the protection decision until those questions are answered. A clear written explanation is more useful than collecting several products without understanding their scope.
FAQ
Does car insurance cover a rented Tesla in Los Angeles?
Your car insurance covers a rented Tesla only when the relevant policy provisions extend to that vehicle, rental arrangement, driver, and use. Confirm liability and damage to the rental separately before pickup.
Does full coverage mean everything on my Tesla rental is covered?
No. The phrase full coverage does not establish the terms of rental protection. Check the purchased coverages, rental provisions, deductibles, exclusions, and contractual charges individually.
Will my credit card cover damage to a rented Tesla?
Your card’s rental benefit covers eligible damage only under its benefit terms. Confirm vehicle eligibility, payment requirements, rental duration, exclusions, and how the benefit interacts with other insurance.
Can another person drive my rented Tesla under my insurance?
Another driver needs authorization under the rental agreement and applicable insurance protection. Ask the rental company and insurer about that person before they drive.
Does FSD (Supervised) mean the car takes responsibility for an accident?
No. FSD (Supervised) requires an attentive driver and does not establish insurance coverage. Responsibility and claim payment depend on the circumstances, applicable law, policy terms, and rental agreement.
Does unlimited mileage mean my insurance covers every road trip?
No. Unlimited mileage is a rental benefit, not confirmation of insurance coverage. Check your route, rental duration, permitted use, and any geographic restrictions separately.
Should I decline the rental company’s damage waiver?
Decide only after comparing the waiver’s terms with your confirmed insurance and card benefits. Check remaining responsibilities, exclusions, and deductibles before accepting or declining protection.
One last thing
Rental reimbursement coverage is not the same as coverage for damage to a rental car. If your policy lists rental reimbursement, ask what that provision pays for; do not treat the name as confirmation that a rented Tesla is protected.
The Suite Escape pairs Los Angeles Tesla rentals with concierge delivery, unlimited miles, and 450+ five-star reviews. Confirm insurance separately, then book the vehicle and delivery arrangements that fit your trip. Premium service and clear protection serve different purposes; your reservation deserves both.
[…] Does your car insurance cover a rented Tesla in LA? […]